Fall Financial Reset: 5 Money Moves to Make Before the Year Ends
There is something about the final stretch of the year that feels like a fresh exhale. The leaves change, the air gets crisp, and for many of us, a quiet but powerful thought surfaces: What did I actually do with my money this year?
If you have been putting off your finances, this is your sign. Not a guilt trip, not a lecture. Just a warm, honest nudge from someone who has sat across from hundreds of women and watched them transform their financial lives, one intentional move at a time.
Fall is the perfect season for a fall financial reset. The year is not over yet, and the decisions you make in the next 60 to 90 days can set you up for a genuinely stronger start to the new year. Whether you are building wealth from scratch or fine-tuning a plan already in motion, these five money moves are worth your attention before December 31st.
Money Move 1: Track Down Where Your Money Actually Went
Review Your Year-to-Date Spending
Before you can fix anything, you need to see what happened. Pull up your bank statements, your credit card history, your e-transfers, all of it, and take an honest look at where your dollars landed from January through today.
You are not looking for reasons to beat yourself up. You are looking for patterns. Subscriptions you forgot about. Dining spend that crept up. Impulse purchases that added up to a number you did not expect. Budget review is not punishment; it is information.
Ask yourself:
Which categories surprised you the most when you looked at the total?
Money Move 2: Max Out Your Tax-Advantaged Accounts Before Year-End
RRSP, TFSA, and RESP Contributions
One of the most powerful things you can do for your future self right now is contribute to your registered accounts before the year closes out.
Here is a quick breakdown for Canadian women doing year-end financial planning:
RRSP (Registered Retirement Savings Plan): Contributions reduce your taxable income for the 2026 tax year. If you have contribution room, use it. The deadline is technically 60 days into the following year, but building the habit of contributing before December gives you more time to plan.
TFSA (Tax-Free Savings Account): Any unused contribution room carries forward, but contributing now means your money starts growing tax-free sooner. Every dollar of growth inside a TFSA is yours to keep.
RESP (Registered Education Savings Plan): If you have children, contributing to an RESP before year-end ensures you qualify for the Canada Education Savings Grant. That is free government money on the table.
These accounts are core tools in wealth building for women, and they are often underutilized simply because no one explained them in plain language. Now you know.
Money Move 3: Revisit Your Financial Goals and Set Q1 Intentions
Give Your Goals an Honest Check-In
At the start of this year, you may have set some financial goals. Now is the time to sit with them, not to judge what you did not accomplish, but to honestly assess where you are and recalibrate.
Did you hit your savings target? Did life shift in a way that changed your priorities? Are the goals you set in January still the right ones for the woman you are today?
Year-end financial planning is not just about wrapping up the year that was. It is about building the bridge into the year ahead. Use what you learned in 2026 to write sharper, more specific goals for Q1. Vague goals do not get funded. Specific goals do.
Think: not “I want to save more money” but “I will automate $300 per month into my TFSA starting January 1st.”
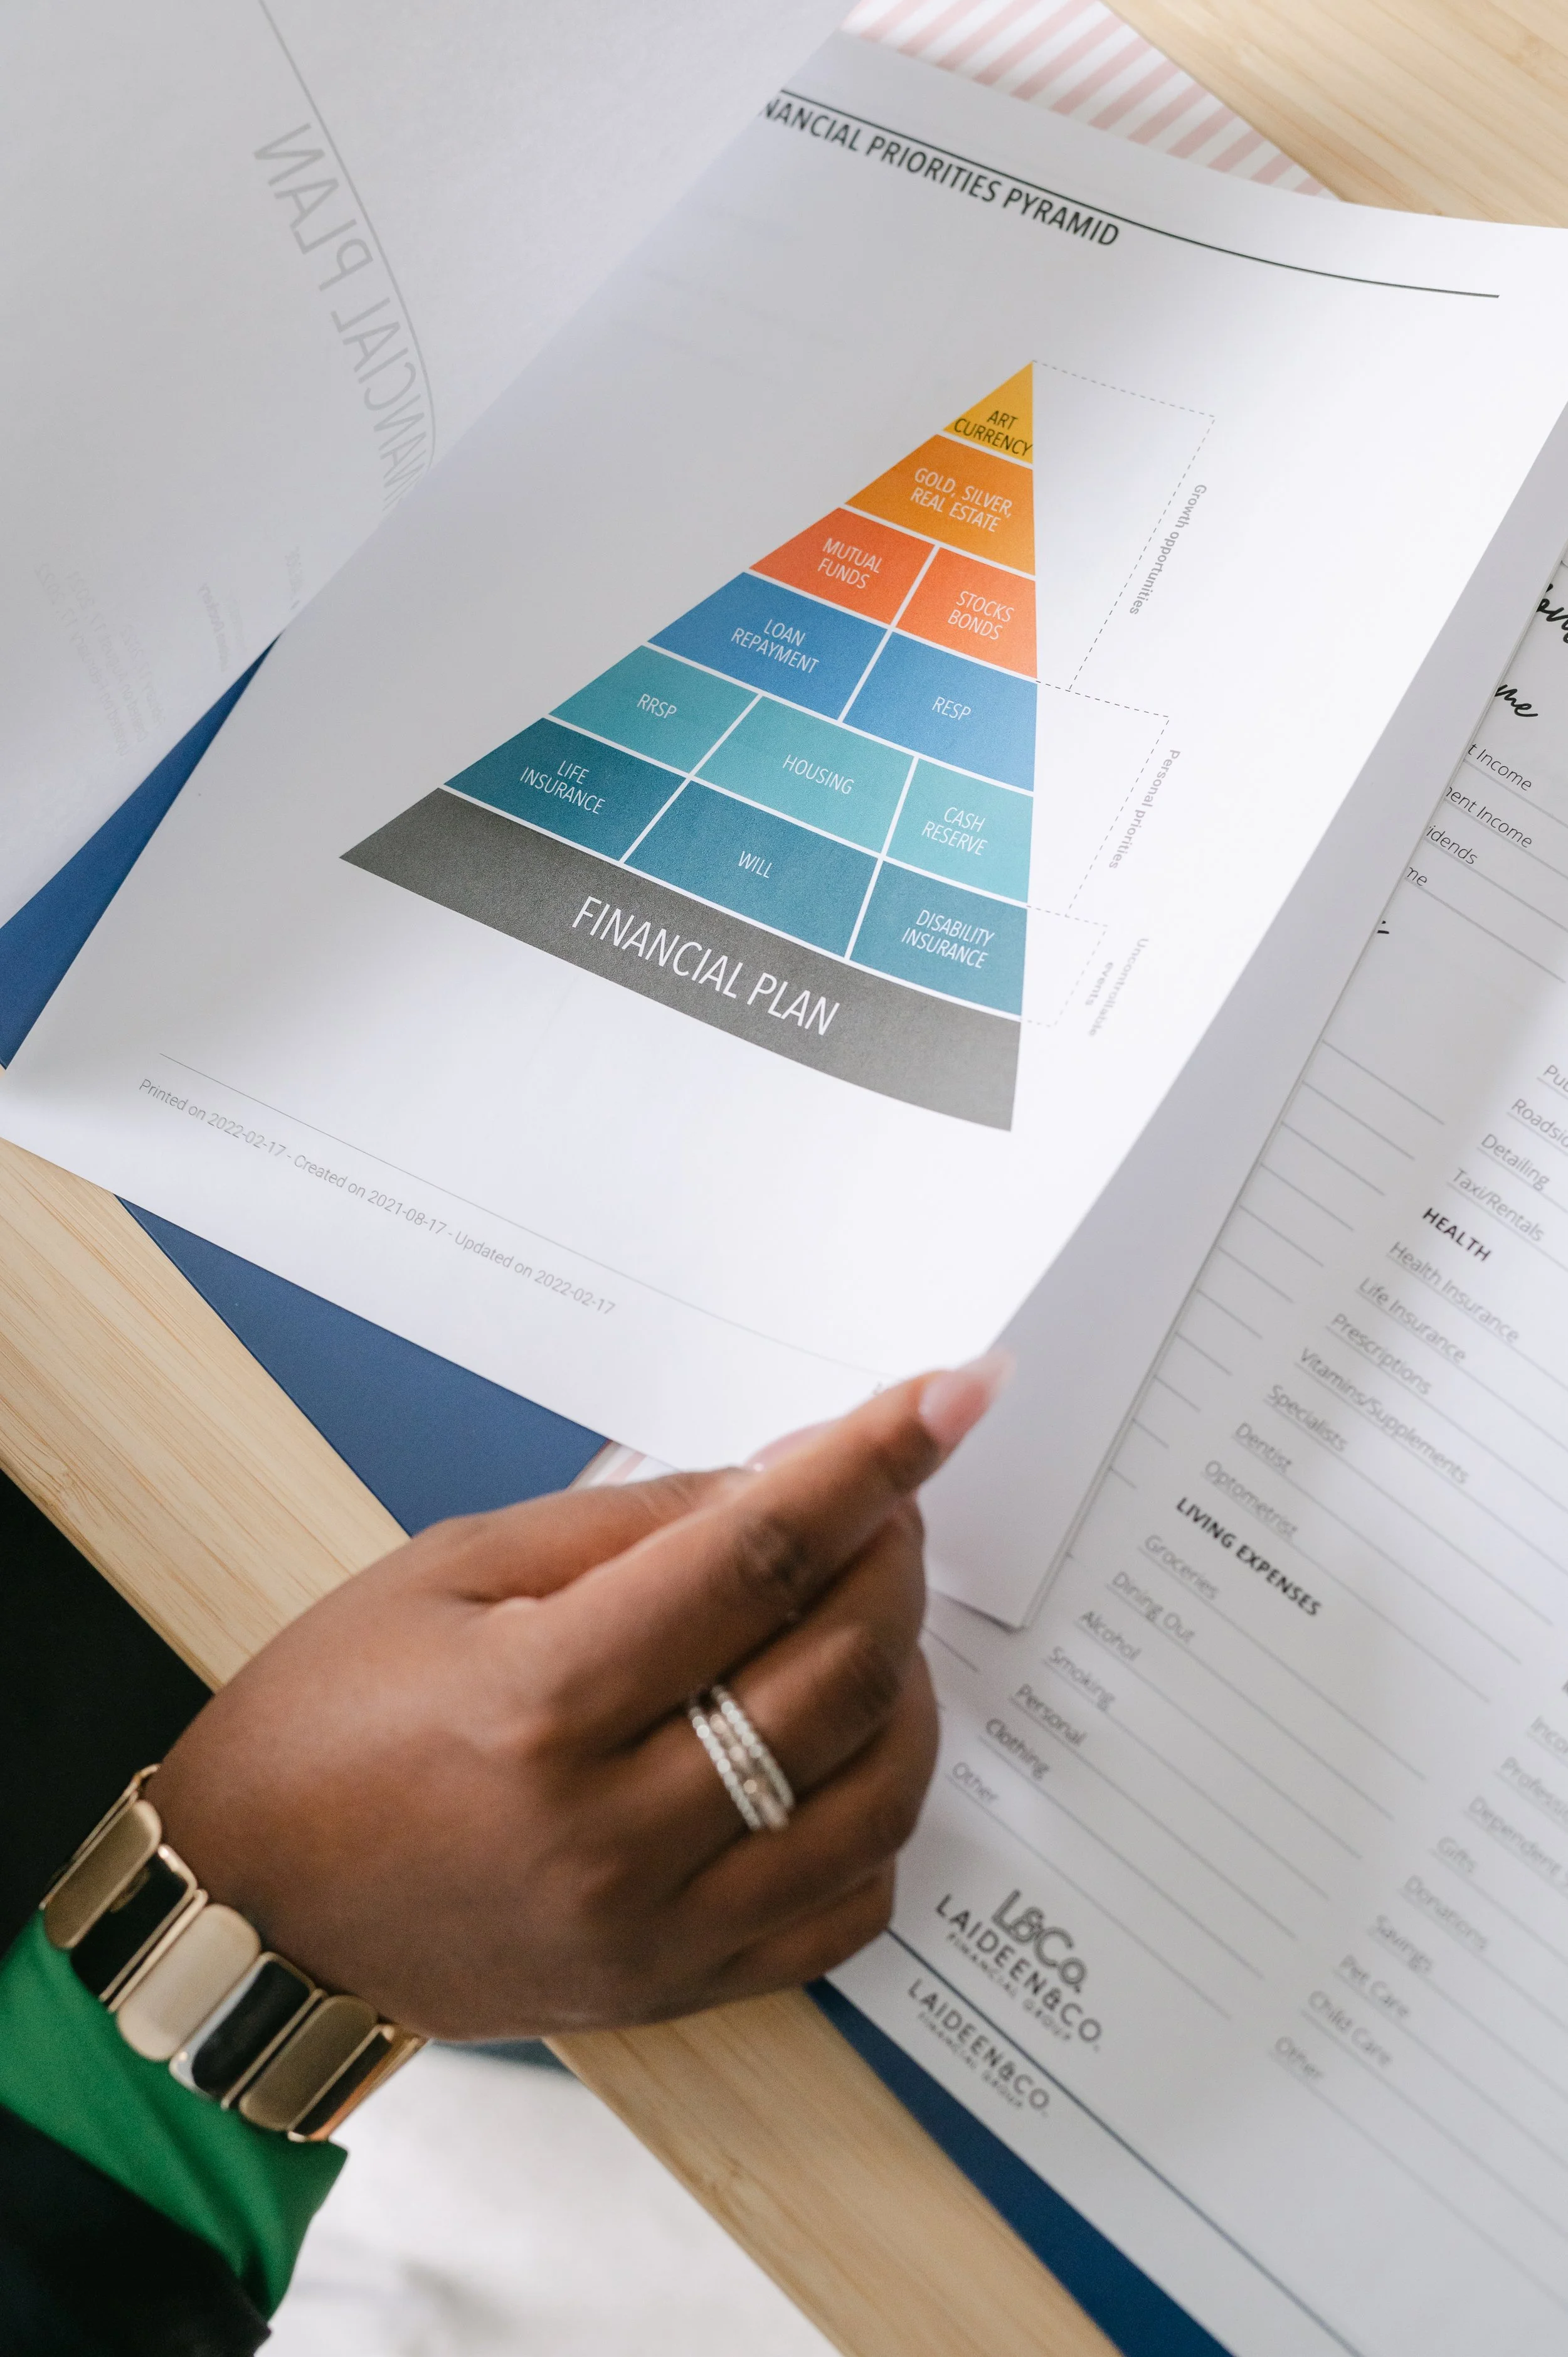
What is the one financial goal you have been avoiding that could change everything if you finally committed to it?
Money Move 4: Review Your Insurance Coverage and Beneficiary Designations
Protect What You Have Built
This is the money move nobody talks about at year-end, and it might be the most important one on this list.
Life changes. You may have gotten married or divorced. Had a child or lost a loved one. Changed jobs or started a business. Each of these events can make your existing insurance coverage outdated, and an outdated beneficiary designation can have serious financial and legal consequences for the people you love.
Take 30 minutes before the year ends to:
Review your life, disability, and critical illness coverage. Is it still enough to protect your income and your family?
Update beneficiary designations on your insurance policies, RRSPs, and TFSAs. Make sure the right people are named.
Confirm that your coverage reflects your current life, not the life you had three years ago.
This is not about fear. It is about being the kind of woman who takes care of the people in her corner, intentionally and proactively.
Money Move 5: Build a Debt Paydown Plan Before January
Start the New Year With a Strategy, Not Just a Wish
Heading into a new year with debt hanging over you does not have to be the story. The last quarter is the perfect time to put a real debt paydown plan in place, so that January feels like a launch, not a repeat of last year.
Start by listing every debt you carry: the balance, the interest rate, and the minimum payment. Then choose your strategy. The debt snowball method (smallest balance first) keeps you motivated with quick wins. The avalanche method (highest interest rate first) saves the most money over time. Either approach works. The one you actually stick to is the right one.
Building a clear plan now, even a simple one, removes the mental load and the financial drag that unstructured debt creates. It is not about perfection. It is about progress with a direction.
You Have More Time Than You Think
The year is not over. The gap between where you are and where you want to be financially can close faster than you expect when you take focused, intentional action.
A fall financial reset is not about fixing everything at once. It is about choosing the right moves, at the right time, so that you step into the new year with clarity and confidence instead of dread.
If you are ready for a personalized financial plan, I would love to connect. Book a free consultation with me at laideenandco.com and let us map out what is possible for you before the year ends.
What is the one money move from this list you are committing to this fall? Drop it in the comments below, ladies. Accountability is one of the most powerful financial tools there is.
Meet Laideen
Laideen Thomas is the founder of Laideen & Co. Financial Group Ltd., a Toronto-based wealth management firm on a mission to help women build multi-generational wealth and make confident financial decisions. With over a decade of experience guiding women through financial planning, investing, insurance, and debt strategy, Laideen brings warmth, expertise, and straight talk to every conversation about money. Connect with her at laideenandco.com.
